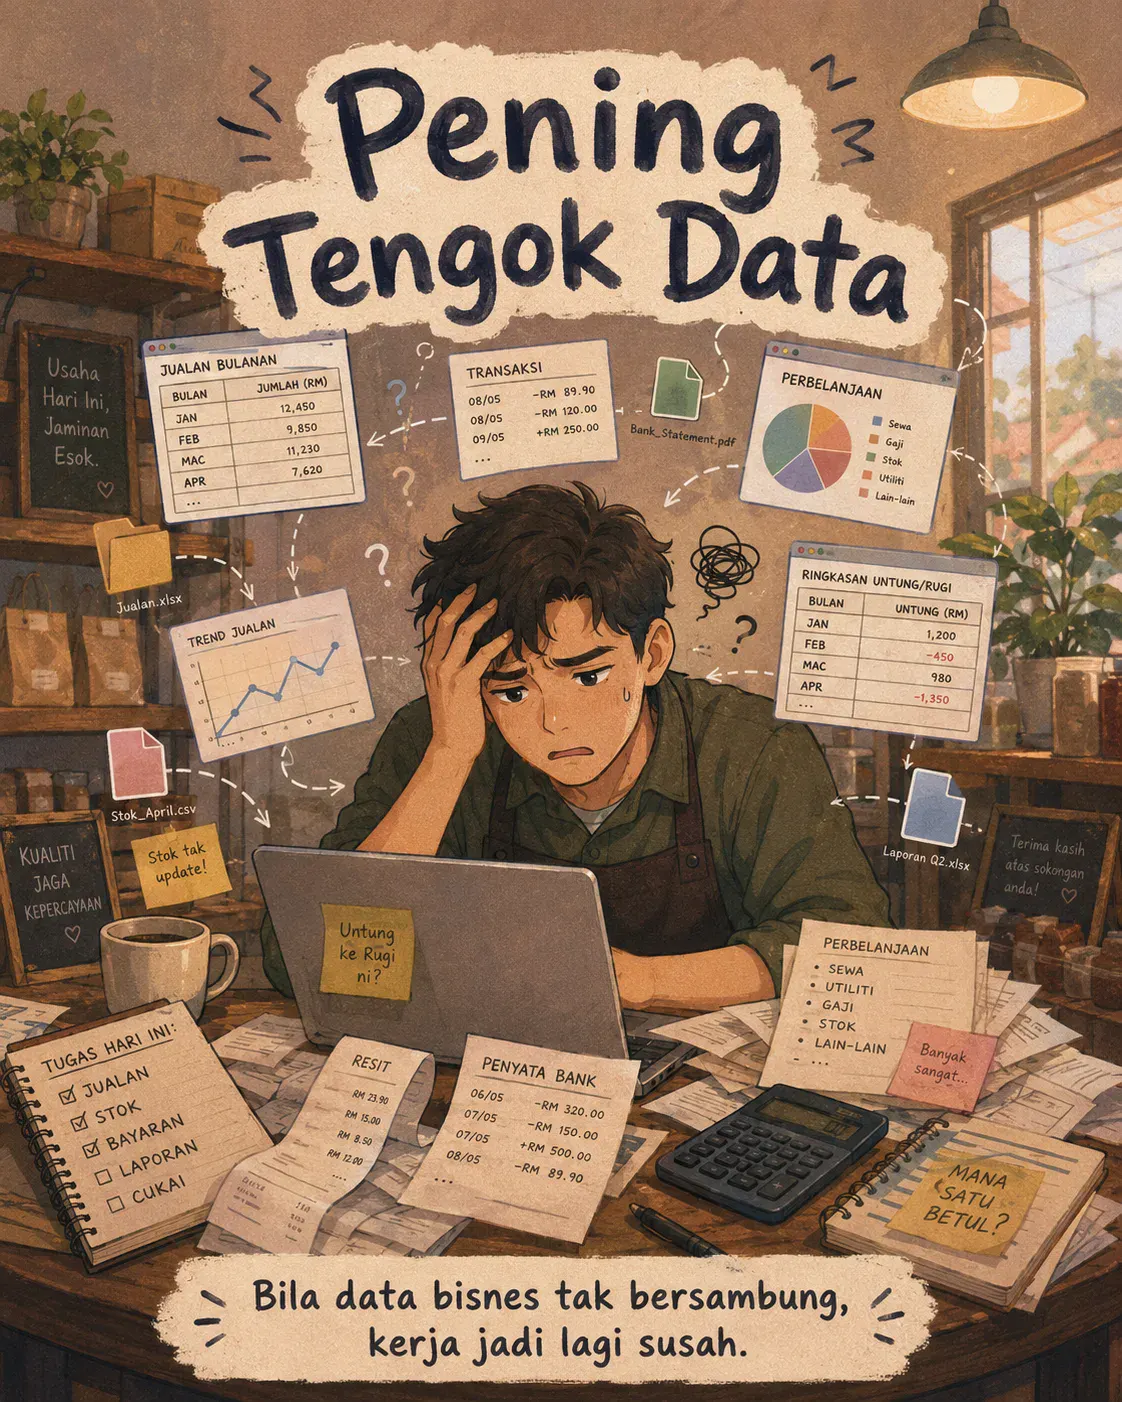
In the last few field deployments I’ve worked with PKS founders, the same gap keeps surfacing: P&L, Lembaran Imbangan, and LHDN readiness. Most agree their financial reporting stack needs to be rebuilt.
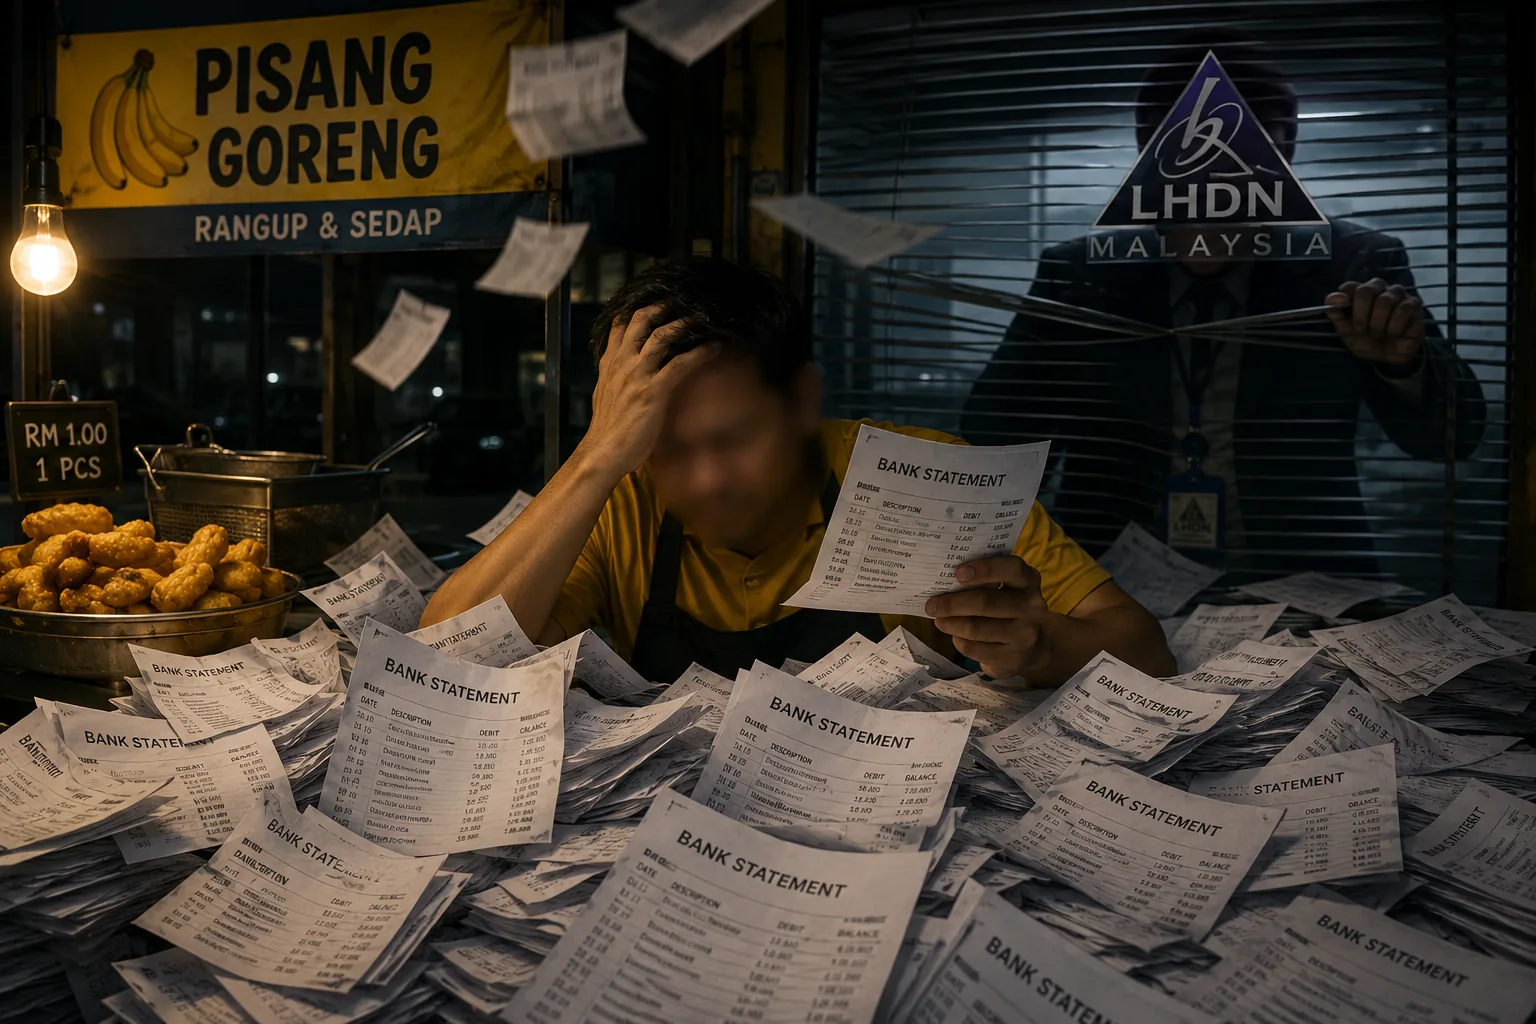
But after years of operations, many PKS still have only one reliable source of truth: their bank statements.
Debtor records are often incomplete. Creditor records may not exist. Fixed assets and inventory are rarely reconciled properly. The auxiliary data layers are broken.
Accrual accounting is the target architecture. But when you’re rebuilding the ledger from scratch, cash records are the most practical entry point.
One founder told me that during an LHDN audit, he was not penalised just because his records were still cash-based. The issue was expenses being reassessed due to wrong classification or tax treatment.
That distinction is critical. Incomplete records are not the same as concealment or tax evasion.
A practical pipeline is: Bank Statement → Clean Cash Ledger → Cash-Based P&L → Accrual Adjustments → P&L + Lembaran Imbangan. This is where AI and automation come in - to ingest, classify, reconcile, and rebuild the financial data layer lebih pantas and more systematically.
My operating principle: Tunai Dahulu. Akrual sebagai Matlamat. Kepatuhan by Design. The right system architecture lets PKS start with existing data and progressively upgrade their financial reporting layer. #PKS #Perakaunan #LHDN #AI #Automasi #FinancialPenyata #MalaysiaSME #NeuralOps



Ruang pembaca
Apa pendapat anda?
Komen disemak sebelum diterbitkan. Email diperlukan untuk moderasi dan tidak dipaparkan kepada pembaca.
Ang artikulong ito ang ipapadala ko sa boss ko.
أعجبني الجزء المتعلق بـ هذا الجزء لأنه عملي وليس نظريًا فقط.
This is where cash-based finally makes sense.
うちのチームも今この説明で悩んでいます。参考になりました。
Good to finally see fixed assets and inventory set out this clearly.