NeuralOps Rangkaian 46 laman · BM
Featured
Teras8
AINNA
Laman utama & hab syarikat
baharu
Propulsion
NeuralOps automation & business systems
ESG
Kelestarian & impak
baharu
Carbon Emulator
Kalkulator jejak karbon & emulator routing pintar
NeuralOps
The intelligent core of the AINNA platform
AINNA Agent
Digital Workforce
Peribadi Infrastruktur AI
Peribadi models and infrastructure for AINNA
Locations
Cari AINNA di Malaysia — Ibu Pejabat dan Panduan Arah
AINNA Agent1
baharu
AINNA Agent
Digital Workforce
Solutions6
Perniagaan & PKS
AI solutions for businesses and PKS
baharu
PKS AI Capability
Latihan, infrastruktur dan sistem perniagaan untuk PKS
Enterprise
Enterprise-grade AI services and operations
Kerajaan & Smart Cities
Selamat AI for government and smart city operations
baharu
PQR1 — Sari Tani
OCR PDF berasaskan projek, halaman terpilih dan semakan QA
Industri
Industry-specific AI operations and launchpads
Teknologi5
Smart Routing
Route each task to the right model and execution path
Sistem Berasingan
AI-built systems that operate independently
Pematuhan AI
Audit, QA and quality control for agents, LLM workflows and Sistem Berasingan
Model & Infrastruktur
Model, compute and infrastructure that power AINNA
Perisikan Data
Market data, analytics and operational intelligence
Proof4
Live Sistem
Interactive NeuralOps systems and demos
Case Studies / Evidence
Teknikal evidence, benchmarks and operational case studies
Penyelidikan
Evidence-backed research across science and engineering
baharu
Collapsible Drying System
Platform pengeringan IoT modular dengan pemantauan anomali Ejen AIik (PoC)
Pelabur5
Pelabur Hub
AINNA investor overview, ask and strategic materials
Pitch Decks
AINNA pitch decks and investor proposals
baharu
AINNA Publishing Grid
Satu teras penerbitan bagi jajaran penerbitan yang berbeza.
Market & Strategy
Hala tuju pasaran, peta jalan logistik dan strategi pemasaran
Teknologi Seni Bina
NeuralOps models, routing and infrastructure architecture
Pasukan12
hab
AINNA Pasukan
Kepimpinan, pakar, dan individu di sebalik AINNA
Pengasas & Ketua Pegawai Eksekutif
Nur Ain Syuhada
Pengarah Strategi Pelanggan
Rozni Enana
Co-Founder & Pengarah Teknikal
Masli Yahaya
Kewangan & Perakaunan
Badrul Haziq
Pengasas Bersama dan Ketua Logistik
Hakim Hafizi
Pengasas Bersama dan Ketua R&D
Muhammad Hakam Hafizul
Operasi & Pembangunan Perniagaan
Muhammad Firdaus Bin Nordin
Operasi E-Dagang
Mohd Shafiq Haiqal
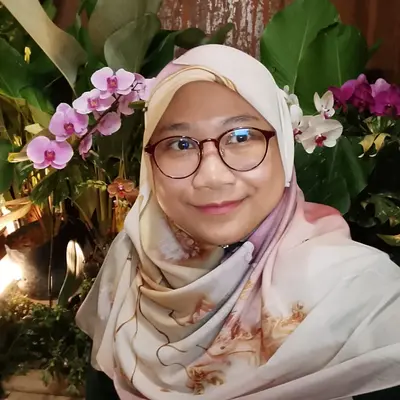
Production Perancangan & Operasi
Siti Nur Najiha
Pembangun Sistem AI
Agent TC
Lead Penyelidikaner
Dr. Abd Razzif Bin Abd Razak
Alat & Experiments2
AI Alat
Katalog utiliti dalam talian percuma
AI Experiments & Permainan
Pusat permainan arked, teka-teki & kad
Content2
AI Insights
Artikel tentang AI & ML
Teknologi Insights
Produk & kejuruteraan
Admin1
hab
Admin
AINNA operations, accounting, and command interfaces